Notes from a European Operator · AI Asset-Manager Observatory · No. 4 · market edition
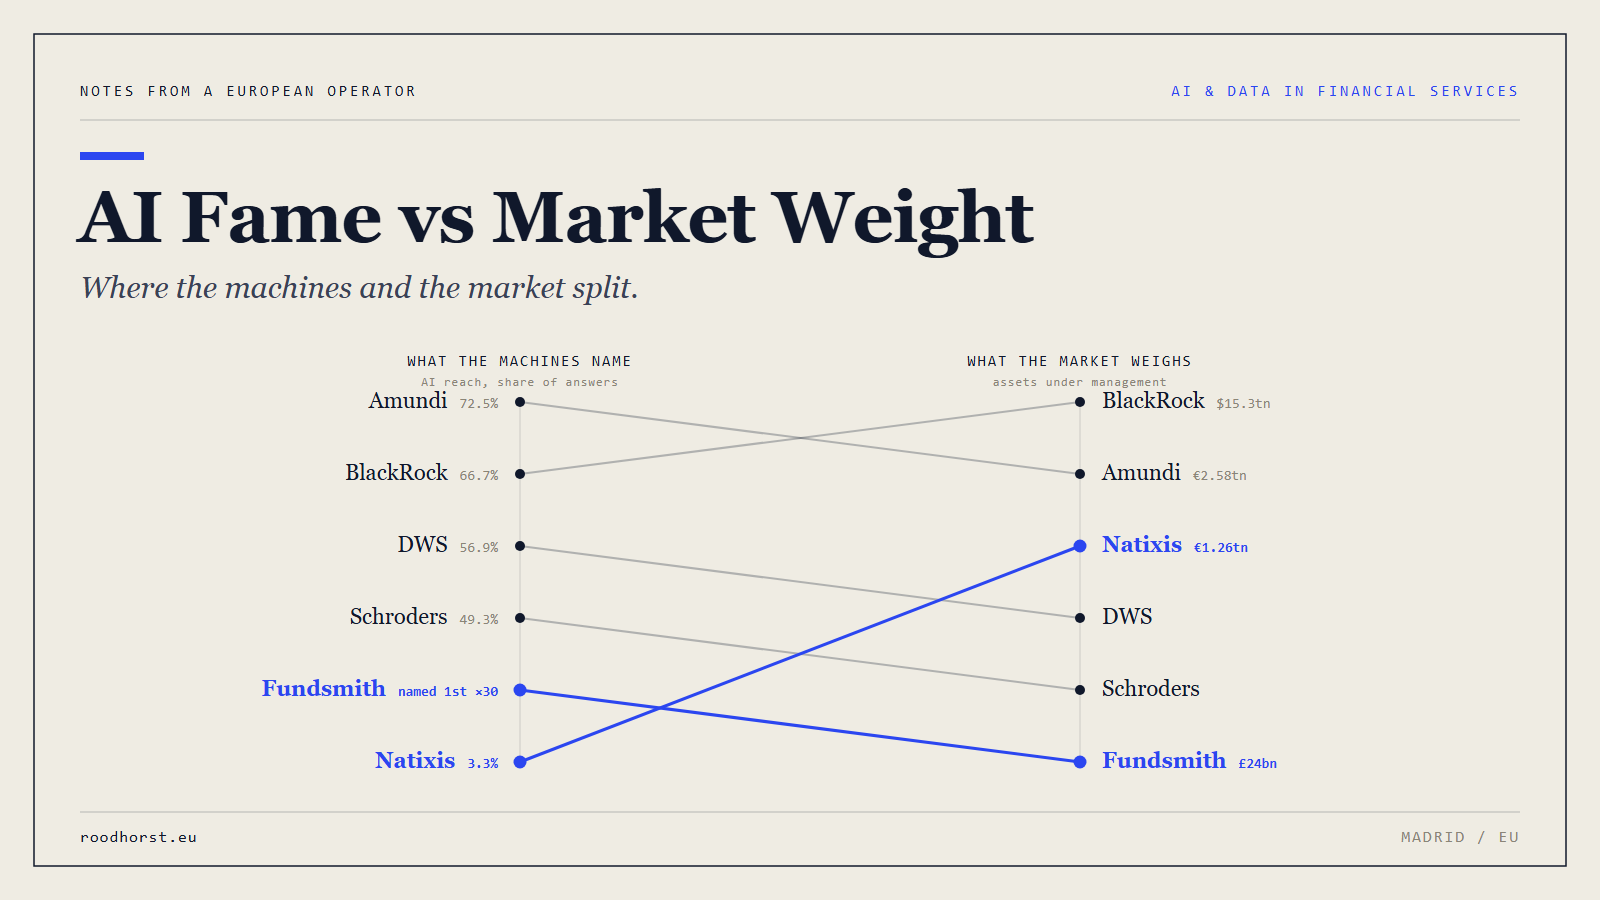
The Observatory’s market edition puts the published 487-answer base run next to reported AUM. The lists agree on Amundi, then split. Natixis runs €1.26 trillion and reaches 3.3% of AI answers. Fundsmith runs £24 billion and is named first thirty times.
Two leaderboards, one overlap
Ask three AI engines to recommend a European asset manager and the answer is a short list of the European asset managers AI recommends most: Amundi, BlackRock, DWS, Schroders, Pictet. Ask the market who actually runs the money and you get a different list: Amundi, UBS, BNP Paribas AM, Natixis, Legal & General. The two lists agree on exactly one firm at the top. Then they diverge.
The AI side is the published base run of the Observatory: 487 answers, three engines, twenty prompts, 104 firms named, every answer saved and validated. The market side is new. It takes each firm’s latest public reporting, December 2025 or H1 2026, and puts reported AUM next to AI reach for the first time. Both views are live in the market edition dashboard. The gap is bigger than the overlap.
Who actually owns European money
Europe’s asset management industry held €33 trillion at the end of 2024 and roughly €34.4 trillion by Q3 2025, about 29% of world fund assets against 52% for the US, per EFAMA. The institutional market alone is €12.2 trillion, per IPE’s Top 500 survey. The top of that market is not what AI answers suggest.
| Firm | Reported AUM | AI reach |
|---|---|---|
| BlackRock | ~$15.3tn · Jun 2026 | 66.7% |
| Amundi | €2.58tn · Jun 2026 | 72.5% |
| UBS Asset Management | ~$2tn · Q1 2026 | 29.6% |
| BNP Paribas AM | >€1.6tn incl. AXA IM · 2026 | 26.7% |
| Natixis IM | €1.26tn · Mar 2026 | 3.3% |
| Legal & General IM | £1,197bn · Dec 2025 | 36.5% |
| DWS | €1.09tn · Dec 2025 | 56.9% |
| Schroders | £824bn · Dec 2025 | 49.3% |
| HSBC Asset Management | $878bn · Dec 2025 | 2.3% |
| Generali Investments | €661bn net · Dec 2025 | 3.3% |
| abrdn | £556bn AUMA · Dec 2025 | 5.9% |
| Union Investment | €535bn · Dec 2025 | 7.0% |
| Deka | €452bn · Dec 2025 | 4.7% |
| Allianz Global Investors | €598bn · Mar 2026 | 23.2% |
| Nordea AM | €325bn · Dec 2025 | 36.1% |
| Robeco | €228bn · Dec 2025 | 42.3% |
| Pictet | CHF 757bn group · Dec 2025 | 43.9% |
| Fundsmith | £24bn · Dec 2025 | 17.9% |
| Comgest | ~€20bn · Dec 2025 | 20.3% |
The pattern is the point. Five firms above €450 billion of reported AUM, Natixis, HSBC, Generali, abrdn and Union, sit below 7% AI reach. Six firms under €250 billion, Robeco, Fundsmith and Comgest among them, sit above 17%. The machines do not rank by size. They rank by what they can find.
What the machines name
The AI list is stable and concentrated: ten firms hold 42% of every mention, the short-list finding that defined this series, and 82% of mentions go to European firms while 18% leak to US giants, the US-leakage note. The list rewards findability, not scale. Three of the top twelve names are not even firms: they are brands of bigger groups. Xtrackers is DWS’s ETF brand. Lyxor is Amundi’s. AXA Investment Managers is now part of BNP Paribas AM.
| Firm | Reach | Mentions | Named first |
|---|---|---|---|
| Amundi | 72.5% | 353 | 124 |
| BlackRock | 66.7% | 325 | 102 |
| DWS | 56.9% | 277 | 11 |
| Schroders | 49.3% | 240 | 0 |
| Pictet | 43.9% | 214 | 17 |
| Robeco | 42.3% | 206 | 19 |
| Vanguard | 40.0% | 195 | 32 |
| Legal & General IM | 36.5% | 178 | 0 |
| Nordea AM | 36.1% | 176 | 10 |
| Xtrackers (brand of DWS) | 32.2% | 157 | 0 |
| UBS Asset Management | 29.6% | 144 | 3 |
| BNP Paribas AM | 26.7% | 130 | 7 |
The named-first column is the brutal one. Fundsmith, £24 billion, was named first thirty times. Schroders, £824 billion: zero. Legal & General, £1,197 billion: zero. Natixis, HSBC, Generali, Union, Deka and abrdn: zero each. UBS Asset Management, three. The firms with the most to lose from a machine shortlist are the ones the machines never put first.
The gap, and what it costs
Mergers make the gap worse before they fix it. BNP Paribas paid €5.1 billion for AXA IM, built a single platform above €1.6 trillion, and the machines still see two firms. Counted as one group, BNP Paribas AM plus AXA IM would reach 53.2% of answers, the second most-named manager in Europe. Counted as two brands, they land at 26.7% and 26.5%. The same split hits Amundi and Lyxor, DWS and Xtrackers, UBS and the Credit Suisse legacy it absorbed.
The cost of the gap is distribution. The engine is a distribution channel and the shortlist is a shelf, the argument of distribution as the new advantage. A €1.26 trillion manager that reaches 3.3% of AI answers is invisible in the channel where buyers now build shortlists. A £24 billion boutique that is named first thirty times owns the top of the answer. Balance-sheet scale does not transfer into that channel. Quotable content does.
If you merged, publish as one entity. Consolidate the pages engines cite: one brand, one story, one dataset. The machines still read BNP and AXA as two firms, and that split is your market share.
If you are a silent giant, your AUM does not transfer. Publish the numbers engines can cite and own one question, the way the Observatory owns the share-of-voice question.
If you are a boutique, you are already winning. Make it structural: publish the definitive dataset for your niche before a bigger firm publishes yours. Want the same read for your firm? The door is the contact page.
The machines do not rank by AUM. They rank by what they can find. Size does not transfer, but a quotable source does.
Sources
- AI Asset-Manager Observatory, base run and method
- The market edition dashboard, AI vs AUM toggle
- The short-list note (10 firms, 42% of mentions)
- The US-leakage note (82% EU / 18% US)
- The multilingual cut
- EFAMA Asset Management Report 2025
- IPE Top 500 Asset Managers 2026
- portfolio institutionell summary of IPE 2026
- Funds Europe, the Trillion Euro Club 2026
- Amundi H1 2026 results
- UBS Q1 2026 results
- DWS 2025 annual report
- Natixis Investment Managers, AUM disclosure
- Legal & General, global AUM
- Pictet FY2025 results
- HSBC Asset Management, AUM disclosure
- Generali Investments, AUM disclosure
- DZ Bank preliminary 2025 figures (Union Investment)
- Deka group key figures 2025
- abrdn FY2025 results
- M&G FY2025 results
- Allianz Global Investors, AUM
- Nordea Asset Management, AUM
- Robeco annual report 2025
- Fundsmith, funds under management
- BNP Paribas AM and AXA IM integration
- BNP Paribas Asset Management
What to do about the gap is set out in how to get your firm named when someone asks AI for a manager.